RBI Repo Rate Hike: How Higher Interest Rates Could Affect Homebuyers and India’s Real Estate Market
The RBI has raised the repo rate from 5.25% to 5.50%. The move could increase borrowing costs for some homebuyers and property developers, but experts believe India’s housing market may remain resilient if demand and economic growth stay strong.

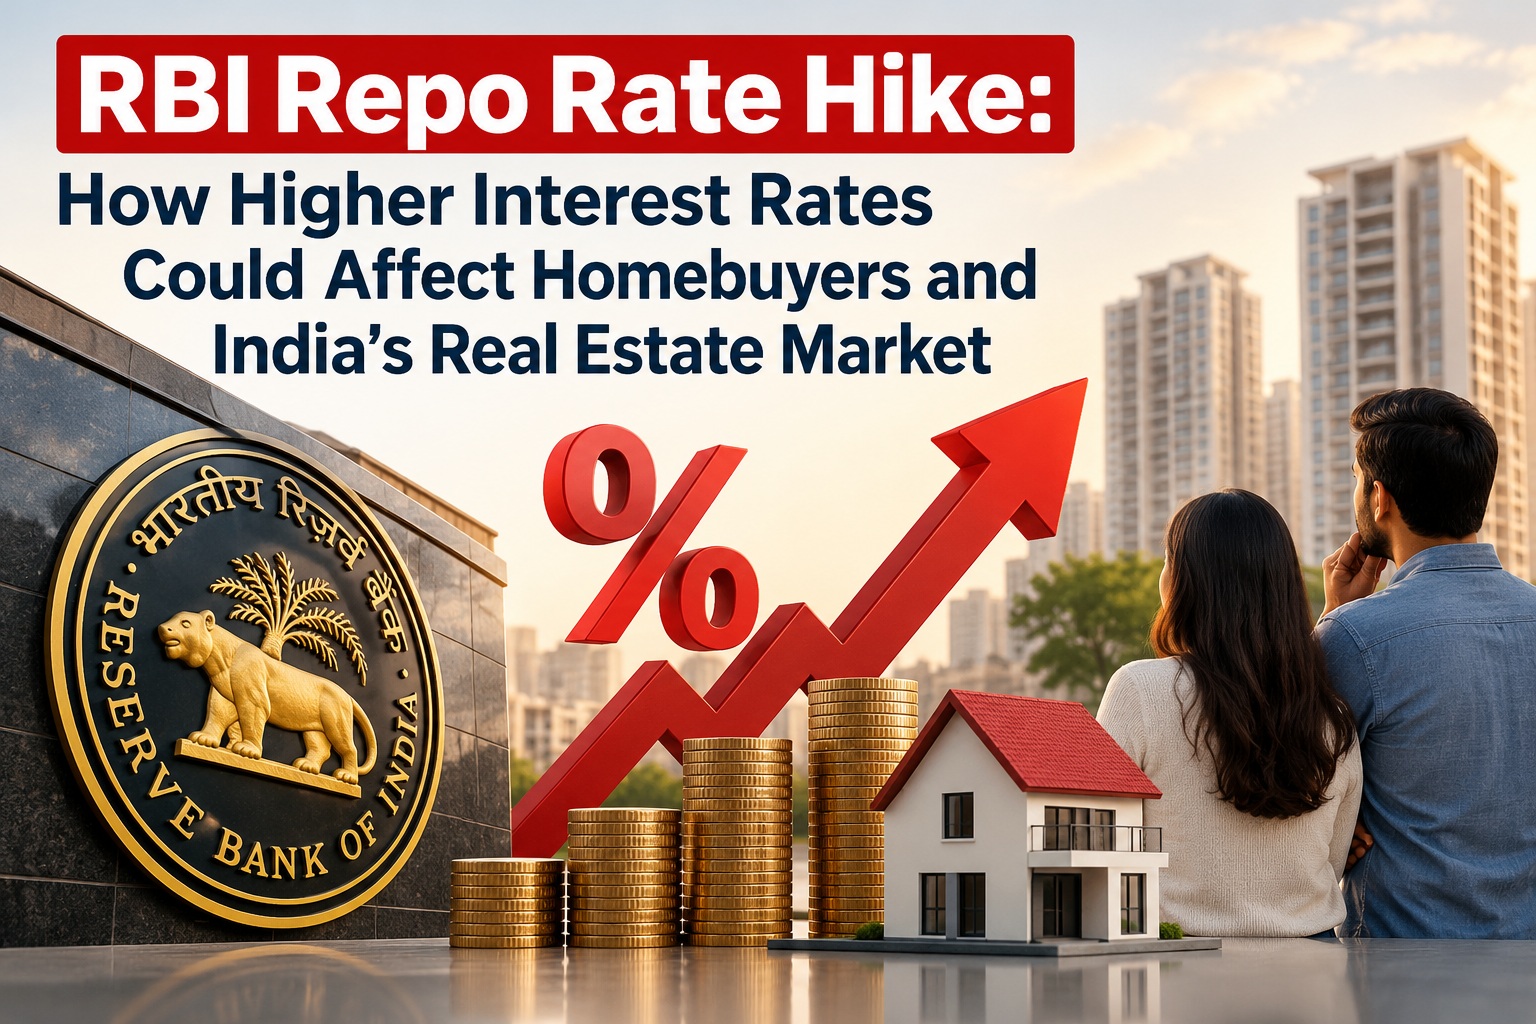
RBI Raises Repo Rate to 5.50%
The Reserve Bank of India (RBI) raised its key repo rate by 25 basis points, from 5.25% to 5.50%, following its monetary policy meeting held from October 5 to 7, 2026.
A basis point is one-hundredth of a percentage point. Therefore, a 25-basis-point increase means an interest-rate rise of 0.25 percentage points.
The decision is important for India’s real estate sector because homebuyers, property developers and investors often depend on bank loans to purchase, construct or develop properties.
The RBI’s decision also comes during the festive season, when many families consider buying a home. Higher borrowing costs could make some buyers more careful about their budgets, particularly those purchasing affordable and mid-income housing.
However, the increase does not automatically mean that every home loan will become more expensive immediately. The actual impact depends on the borrower’s loan agreement, interest-rate benchmark and the lender’s decision.
Why Has the RBI Increased the Repo Rate?
The repo rate is the interest rate at which the RBI lends short-term funds to banks against eligible securities. It is one of the tools the central bank uses to manage inflation, liquidity and economic activity.
When inflationary pressures rise, the RBI may increase interest rates to make borrowing more expensive and moderate demand across the economy.
In its October 2026 policy decision, the RBI raised the repo rate and shifted its policy stance to “calibrated tightening”. The central bank indicated that near-term rate cuts were not expected under the prevailing conditions, while future decisions would depend on inflation and economic developments.
For the real estate sector, this creates a new challenge after a period in which lower interest rates had helped support borrowing and housing demand.
Higher interest rates can affect the cost of home loans, construction finance and property development. But the scale of the impact will depend on how banks and other lenders respond to the RBI’s decision.
How Will the Repo Rate Hike Affect Homebuyers?
The most direct concern for many homebuyers is the monthly equated monthly instalment, commonly known as the EMI.
For people taking a floating-rate home loan linked to an external benchmark such as the repo rate, a change in the benchmark can lead to a change in the loan’s interest rate, subject to the lender’s reset terms.
This may result in a higher EMI, a longer repayment period, or a combination of both.
For example, consider a homebuyer with a ₹30 lakh home loan for 20 years at an illustrative annual interest rate of 8%.
If the interest rate increases to 8.25% and the entire 0.25-percentage-point increase is passed on, the monthly EMI would rise from approximately ₹25,093 to ₹25,562, assuming the remaining loan period stays at 20 years.
That means the borrower would pay around ₹469 more each month, or approximately ₹5,628 more over a year.
These figures are illustrative, not a prediction of what every bank will charge. Actual EMIs depend on the outstanding loan balance, remaining tenure, lender’s rate and the date on which the revised rate takes effect.
For a family already managing school fees, household expenses and other loan payments, even a modest increase can affect monthly budgeting.
Will Every Home Loan Become More Expensive? No. The RBI’s repo rate decision does not automatically change the interest rate on every home loan. The impact depends on the type of loan and its terms.
Floating-rate loans: Borrowers may face a higher interest rate when the relevant benchmark is revised and the lender passes on the change.
Fixed-rate loans: The interest rate generally remains unchanged for the agreed fixed-rate period, subject to the terms of the loan contract.
New home loans: Buyers applying for a loan may receive an offer based on the lender’s current pricing, credit assessment and other applicable conditions.
Borrowers should check their loan statements and ask their lender whether their loan is linked to the repo rate, another external benchmark or an internal benchmark.
RBI rules also provide borrowers with options at interest-rate resets for covered equated-instalment personal loans. Depending on the applicable terms, these may include an increase in EMI, an extension of the repayment period, switching to a fixed rate where offered, or making a part or full prepayment.
Before making a decision, borrowers should compare the long-term cost of each option rather than focusing only on the next monthly payment.
Will Higher Interest Rates Reduce Housing Demand?
The effect on housing demand may not be the same across every segment of the market.
Buyers who depend heavily on home loans are generally more sensitive to changes in interest rates. This is particularly relevant for first-time buyers and households looking at affordable or mid-income homes.
If property prices and monthly EMIs rise together, some buyers may reduce their budget, search for a smaller home, negotiate harder or delay their purchase.
A report by Moneycontrol on October 7 noted that the repo rate increase could put pressure on festive-season housing demand, particularly in price-sensitive segments. Industry experts also indicated that the increase alone was unlikely to derail the broader housing market unless borrowing costs rose further or remained elevated for an extended period.
This distinction matters. A higher EMI can make a property less affordable for an individual buyer without necessarily causing a major fall in property prices across an entire city.
The market response will also depend on employment, household incomes, available housing supply, property prices, buyer confidence and the quality of projects being offered.
What Does the Rate Hike Mean for Property Developers?
Homebuyers are not the only ones who may feel the impact. Real estate developers often borrow money to purchase land, finance construction and complete projects.
If lenders increase borrowing rates, developers may face higher financing expenses. This can put pressure on project margins, especially where construction costs are already high or sales are slower than expected.
Developers may respond by reviewing project budgets, managing cash flows more carefully, offering payment plans or focusing on projects with stronger demand.
Projects that depend heavily on borrowed money or require a long period to generate sales may face greater pressure than projects supported by strong customer demand and disciplined financial planning.
Higher financing costs can also affect investment decisions. Investors may reassess expected returns, property valuations and the time required to recover their money.
For this reason, financial discipline, timely project completion and careful selection of new projects will be important for developers in the coming months.
What Are Real Estate Industry Leaders Saying?
Industry leaders have expressed a mix of caution about borrowing costs and confidence in the sector’s longer-term prospects.
Ashish Bhutani, CEO of Bhutani Infra, has highlighted the support that real estate receives from rising incomes, urbanisation, infrastructure development and the continuing desire of families to own homes. His assessment emphasises the need for developers to maintain financial discipline, complete projects on time and concentrate on projects backed by genuine demand.
Sahil Agarwal, CEO of Nimbus Group, has described the RBI’s decision as part of its effort to maintain macroeconomic stability and manage inflation. He has also pointed to healthy housing demand, consumer confidence and interest in quality residential and plotted developments as factors supporting the sector.
Agarwal expects demand to remain steady across metropolitan markets and Tier-2 and Tier-3 cities, supported by infrastructure growth and opportunities in emerging markets.
These views reflect confidence in the sector’s underlying demand, but they should not be interpreted as a guarantee that every property market or project will perform well. Local demand, pricing, financing and project quality will continue to influence outcomes.
Why Infrastructure and Location Still Matter
Interest rates are only one factor that determines whether a property is a good purchase.
Infrastructure development, connectivity, employment opportunities, public transport, access to schools and hospitals, and the supply of homes in a particular area can all influence demand.
In cities such as Noida and Greater Noida, buyers should assess the specific location and project rather than assuming that all properties will benefit equally from regional growth.
A property near established employment centres and reliable transport links may attract a different level of demand from one where promised infrastructure is still under development.
Buyers should also compare the total purchase cost, including registration charges, maintenance, taxes and interiors, with their expected monthly income and long-term financial commitments.
For investors, rental demand, vacancy periods, maintenance expenses, resale liquidity and realistic rental yields are equally important. A property should not be considered a sound investment simply because its advertised price is expected to rise.
Will the Impact Be Different in Affordable, Mid-Income and Premium Housing?
Yes. The impact can vary by price segment.
Affordable housing: Buyers often have tighter budgets and may depend more heavily on loans. A rise in EMI can make a meaningful difference to affordability and may lead some buyers to delay purchases.
Mid-income housing: Buyers may have greater financial flexibility than affordable-home buyers, but higher property prices and loan repayments can still affect purchase decisions.
Premium housing: Some buyers may be less dependent on borrowing, which can reduce their immediate sensitivity to a rate increase. However, this does not make the premium segment immune to changes in economic conditions or buyer confidence.
The overall effect will depend on the size and duration of any further rate changes, along with income growth, property prices and the availability of attractive projects.
What Should Homebuyers Do Now?
People planning to buy a home should avoid making decisions based only on expectations that interest rates will rise or fall again.
First, calculate the EMI using a slightly higher interest rate to check whether the household budget can absorb a possible increase.
Second, keep enough savings for emergencies, registration expenses, moving costs and other home-related payments. Avoid using all available savings for the down payment.
Third, compare loan offers carefully. Look at the interest rate, processing fees, benchmark, reset frequency, prepayment conditions and total repayment cost.
Fourth, assess the property itself. Verify the project’s legal documents, RERA registration where applicable, construction status, possession timeline and the developer’s track record.
Finally, negotiate based on the actual market and the property’s value. Buyers should not rush into a purchase simply because a developer is offering a festive discount or because they fear that rates may increase further.
What Should Property Developers Do?
Developers should review their borrowing costs, construction budgets and expected cash flows under different interest-rate scenarios.
They should focus on completing existing projects, maintaining transparency with buyers and avoiding excessive dependence on short-term borrowing.
Pricing and payment plans should reflect the real purchasing capacity of customers. Projects supported by genuine end-user demand and sound financial planning may be better placed to manage a period of higher borrowing costs.
For developers entering new markets, careful research into local demand, employment growth, infrastructure and competing supply will be essential.
The Bigger Picture: A Cautious but Not Negative Outlook
The RBI’s repo rate increase is a development that homebuyers and real estate companies should monitor closely. It may increase borrowing costs for some customers, place pressure on affordability and make developers more careful about financing.
However, a 25-basis-point increase by itself does not establish that India’s real estate market is heading for a slowdown. The wider outlook will depend on inflation, future RBI decisions, household incomes, property prices, employment and the strength of end-user demand.
The key question is whether the increase remains a limited adjustment or becomes part of a longer period of tighter monetary policy.
For homebuyers, the practical priority is to purchase within their financial capacity. For developers, it is to maintain sound finances and deliver projects on time. For investors, it is to judge properties on location, rental potential, price and risk—not on optimistic growth expectations alone.
The takeaway: Higher interest rates may make property purchases more expensive for some buyers, but the long-term performance of real estate will still depend on affordability, infrastructure, genuine demand and the financial strength of individual projects.
- Reserve Bank of India (RBI) — Monetary Policy Statement, October 5–7, 2026. Read the policy statement
- Moneycontrol — “Repo rate hike to push up home loan EMIs, put pressure on festive housing demand, say experts,” October 7, 2026. Read the report
- Business Standard — “RBI rate hike may pressure housing affordability, but demand seen resilient,” October 7, 2026. Read the report
- Reserve Bank of India — FAQs on changes in floating-rate EMI-based loans and borrower options. Read the RBI FAQs
- Moneycontrol — “October repo rate hike could dent festive housing demand, impact developer financing,” October 1, 2026. Read the report
- Fortune India — “Nifty Realty Index Drops 2% as RBI Hikes Rates; Real Estate Industry Monitors Borrowing Costs.” Read the report
Report a mistake
Related stories
Jio Platforms IPO: Mukesh Ambani’s Digital Giant Attracts $77 Billion in Bids
Odisha CM Mohan Charan Majhi to Attend India Chem 2026 in Mumbai
Marco Rubio Visits Reliance’s Jamnagar Refinery, Discusses Energy and Technology Partnerships
Reader comments (0)
No comments yet. Be the first.